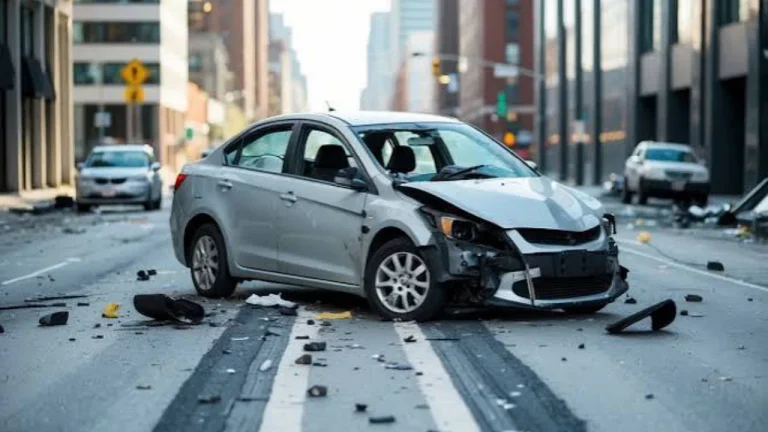
The first three days after a crash shape most personal injury claims more than any other stretch of time, and the decisions you make in that window are hard to undo. Evidence disappears, insurers start building their version of events, and injuries that feel minor often turn out to be serious. Knowing which steps matter most, and in what order, protects both your health and your right to compensation. See also: the attorneys at Theisen & Roche.
Key takeaways
- Get medical evaluation within 24 hours, even if you feel fine.
- Photograph the scene, vehicles, and visible injuries before anything is moved.
- Do not give a recorded statement to the other driver’s insurer without advice.
- Keep a daily log of pain, missed work, and appointments.
- Illinois generally allows two years to file a personal injury lawsuit, but evidence goes much faster.
Why the first 24 hours matter for your medical record
Many injuries from collisions, including concussions, soft-tissue damage, and internal bleeding, do not produce obvious symptoms right away. Adrenaline can mask pain for hours. An insurer will often argue that a gap between the crash and your first treatment means the injury came from something else.
Seeing a doctor promptly creates a clear link between the accident and your condition. Follow every recommended test and appointment. Missed follow-ups are one of the easiest ways for an adjuster to reduce what your claim is worth.
Evidence that disappears quickly
Skid marks fade, traffic camera footage is often overwritten within weeks, and vehicles are sent to salvage yards. Your phone is usually the best tool you have at the scene. Take wide shots showing traffic signals, road conditions, and vehicle positions, then close-ups of damage and any injuries.
Collect names and contact information from witnesses while they are still nearby. A short voice memo describing what happened, recorded while your memory is fresh, can be valuable later. Use a notes app with timestamps rather than trying to reconstruct details from memory weeks afterward.
Handling the insurance adjuster
An adjuster from the at-fault driver’s insurer may call within days and sound friendly and helpful. Their job is to limit payout. A recorded statement can be used to challenge your account, and an early offer is often far below what a claim is worth once future treatment and lost income are counted.
You are not required to accept the first offer or agree to a recorded statement before you understand your options. Politely take the adjuster’s contact details and say you will respond after reviewing your situation. The cost is a slower process, but it leaves you with more control over the outcome.
Tracking losses in a daily journal
Insurers and courts weigh what they can document. A simple daily entry covering pain level, medications, activities you could not do, and time missed from work gives your claim concrete support. Keep receipts for prescriptions, rides to appointments, and childcare you had to arrange.
Lost wages should be documented with a letter from your employer showing dates missed and pay rate. Gaps in this paper trail are hard to fill in later, so start the log the same day as the crash and keep it up through recovery.
Worked example: why early offers mislead
Suppose you had $6,000 in emergency room and imaging bills, missed three weeks of work earning $1,000 per week, and your doctor expects six more months of physical therapy at roughly $300 per month. Step by step: the medical bills already total $6,000; the lost wages are 3 × $1,000, or $3,000; the expected therapy is 6 × $300, or $1,800. Added together, the known economic losses reach $6,000 + $3,000 + $1,800, or $10,800, before pain and suffering is considered. An offer of $4,000 made in the first week ignores most of that picture, and it does not cover treatment that continues after the money is paid.
Accepting a settlement generally ends the claim, so make that decision only once your medical picture is clear.
When to get legal help
Consulting a lawyer does not mean you are headed to trial. Many personal injury firms work on contingency, meaning no fee unless they recover compensation. For serious injuries, disputed fault, or multiple insurers involved, an early consultation with the attorneys at Theisen & Roche can clarify your options before you sign anything. A general guide such as When Should You Call a Personal Injury Lawyer in Reisterstown? can help you decide whether your situation fits the usual warning signs.
Appointments and the timing of documents also matter for a claim, so planning them carefully helps. The principles in Service Scheduling: How Appointment Planning Influences Customer Trust apply to medical follow-ups as much as to any other service you rely on.
The real risk: waiting too long
The biggest danger is rarely a wrong decision. It is a delayed one. Evidence fades, memories blur, and treatment gaps accumulate, and each gap gives an insurer another argument to use against you. Acting within the first few days gives you the strongest position, even if you are not ready to file anything yet. Gather your records, keep your log, and speak with a lawyer before you accept any payment or sign a release.
About the Author